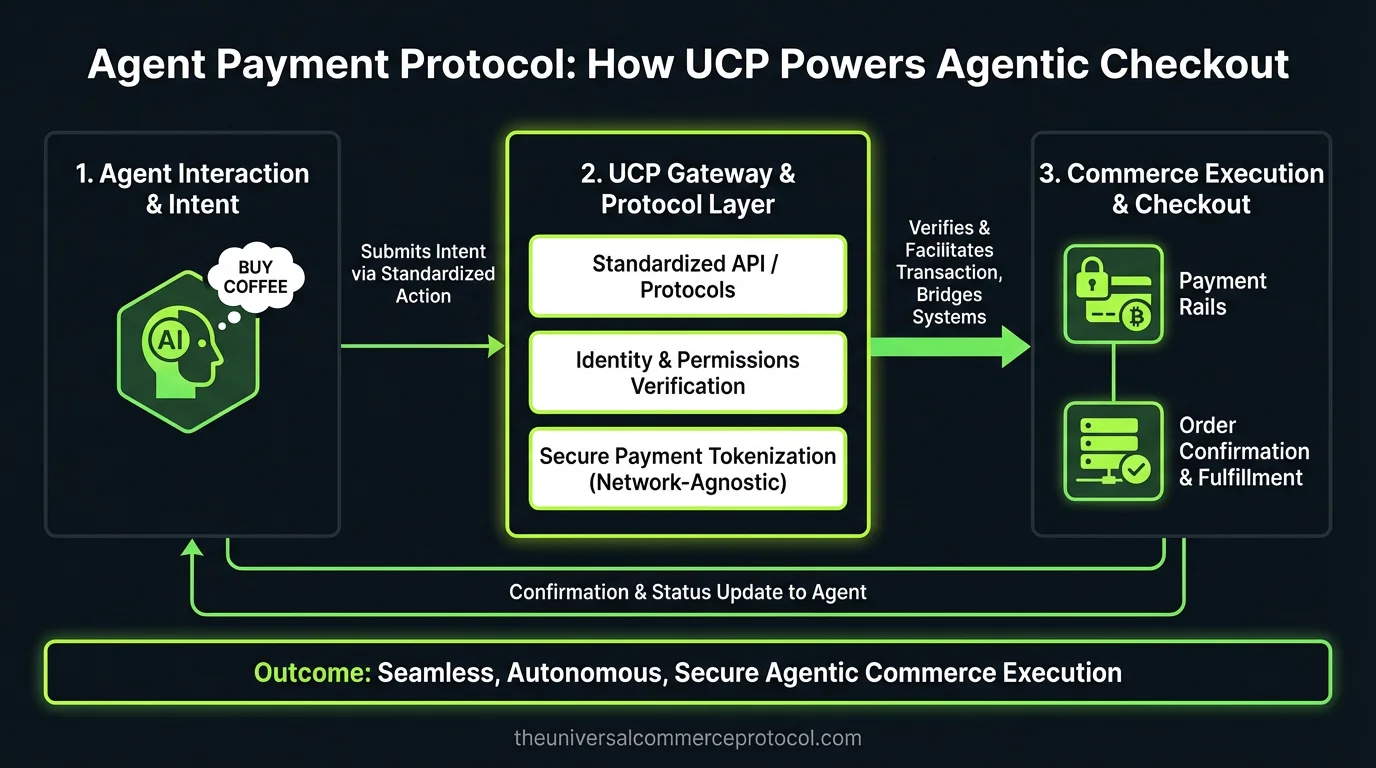
Agent payment protocol is the technical infrastructure that allows AI agents — like Google’s Gemini, OpenAI’s ChatGPT, and other autonomous shopping assistants — to initiate, authorize, and complete financial transactions on behalf of human users without requiring manual intervention at each step of the checkout process.
If you’re a merchant, developer, or commerce platform, the Universal Commerce Protocol (UCP) is the open standard at the center of it.
Spec note (Nov 2026): The current UCP specification is v2026-08-25; Google merchant surfaces implement v2026-04-08. AP2 is carried in UCP as extension dev.ucp.common.payment.ap2_mandate.
What Is Agent Payment Protocol?
An agent payment protocol defines how an AI agent proves it has authorization to spend money, selects a payment method, executes a transaction, and returns a cryptographically verifiable receipt — all without the buyer typing a card number or clicking a “Pay Now” button.
The concept emerged from a practical problem: as AI agents began handling shopping tasks autonomously, no standard existed for merchants to trust that an agent genuinely had user consent. A rogue agent could theoretically impersonate a buyer. An agent from one platform couldn’t seamlessly pay on a merchant that used a different payment system. The protocol layer solves both problems.
The two most significant agent payment protocols in production or active development today are:
- UCP’s native payment handler model — part of the Universal Commerce Protocol using OAuth 2.0 identity linking and Google Pay for payment execution inside Gemini and AI Mode
- AP2 (Agent Payments Protocol) — a cryptographic consent-verification layer compatible with UCP that issues payment mandates with verifiable user intent attached to every authorization
AP2 status (Nov 2026): Donated to FIDO Alliance April 28, 2026; as of Oct 31, 2026 no FIDO spec published and no live Google product documented as using AP2 in production; pre-1.0 schemas can change.
How Agent Payment Protocols Actually Work: Step by Step
Understanding the mechanics requires walking through an actual agentic checkout flow. Here’s what happens when a buyer tells their AI assistant to “order the same running shoes I got last time, but in size 10”:
- Capability discovery — The agent queries the merchant’s
/.well-known/ucpendpoint to understand what checkout and payment methods the merchant accepts - Identity linking — The agent presents OAuth 2.0 credentials confirming the buyer has previously authorized this agent to act on their behalf with this merchant
- Cart construction — The agent builds a checkout session with line items, shipping preferences, and fulfillment options, all in UCP’s standardized JSON format
- Payment handler selection — The merchant responds with compatible payment handlers for this specific transaction; the agent selects Google Pay or another available method from the buyer’s wallet
- Authorization and execution — The payment is executed; AP2 attaches a cryptographic payment mandate documenting that the specific user authorized the specific transaction at a specific time
- Order confirmation — A structured confirmation record is returned to the agent, which surfaces it to the buyer in natural language
The buyer never leaves their AI assistant’s interface.
UCP vs. Traditional Payment APIs: What’s Different
Traditional payment APIs — Stripe, Braintree, PayPal — were designed for humans interacting with a merchant’s checkout UI. The merchant controls the page. The buyer types their credentials. The payment API handles the money movement.
Agent payment protocols invert this architecture. The AI agent is the interface. The merchant no longer controls the presentation layer. This creates a fundamentally different trust problem:
| Dimension | Traditional Payment API | Agent Payment Protocol (UCP) |
|---|---|---|
| Interface controller | Merchant | AI agent / platform |
| User consent verification | Implicit (user is present at checkout) | Explicit (AP2 signed checkout/payment mandates as evidence of intent) |
| Payment method discovery | Merchant-defined options | Dynamic handler negotiation per transaction |
| Cross-platform interoperability | Merchant integration required per platform | Open protocol — any UCP-compatible agent works |
The $23 CPC Signal: Why Agentic Payments Are Attracting Enterprise Capital
The commercial logic is straightforward. Mastercard launched its Verifiable Intent framework specifically to address trust in agent-initiated transactions.
Every one of those institutions needs to integrate with — or build compatible alternatives to — the protocols that AI platforms actually use. Right now, that means UCP for Google’s ecosystem and the emerging AP2 layer for cross-platform cryptographic consent.
What Merchants Need to Do to Support Agent Payment Protocol
For merchants on other platforms, or those running custom commerce stacks, the key readiness steps are:
1. Publish the /.well-known/ucp Discovery Endpoint
This JSON file advertises your merchant capabilities to AI agents — what checkout features you support, which payment handlers you accept, your OAuth authorization server configuration. Without it, AI agents cannot discover your store as UCP-compatible.
2. Configure OAuth 2.0 Identity Linking
3. Implement Google Pay as a Payment Handler
Google Pay is the primary payment execution method for Gemini-mediated transactions. Merchants without Google Pay integration will not be eligible for native UCP checkout inside Google AI Mode or the Gemini app.
Agent Payment Security: How UCP Protects Buyers and Merchants
The security architecture of agent payment protocols is substantially more rigorous than traditional checkout for one reason: the buyer isn’t present to visually verify what they’re purchasing. Every safeguard in the protocol compensates for that absence.
Cryptographic payment mandates (AP2) ensure that every authorization has documented user intent attached. If a transaction is disputed, the merchant can produce a verifiable record of exactly what the buyer authorized and when.
OAuth 2.0 scope limitation means buyers can authorize agents to shop within specific constraints — a spending limit, a category restriction, or a time window. Agents operate within those parameters or escalate to the buyer for approval.
The Competitive Landscape: Who Owns Agent Payment Infrastructure
UCP is an open protocol, but the payment execution layer runs through platform-native infrastructure. For Google’s AI surfaces, that means Google Pay.
This creates a fragmented but converging picture. Merchants who optimize for one platform’s agentic checkout gain disproportionate access to that platform’s buyers. The open protocol layer (UCP) provides the interoperability foundation; the payment execution layer remains platform-specific for now.
Live-status update (Nov 2026): Direct UCP checkout is live in the US (Universal Cart launched Oct 15, 2026) and live for Canadian shoppers on AI Mode and Gemini since Nov 4, 2026 (lululemon, select Shopify merchants, Shoppers Drug Mart, Simons; retailer remains seller of record). Merchant Center self-serve UCP integration follows in 2027.
Visa and Mastercard have both published roadmaps for agent-compatible payment infrastructure. Mastercard’s Verifiable Intent framework, announced in early 2026, addresses the cryptographic consent gap directly. The pattern is consistent: every major payments and commerce infrastructure provider is building for the agentic use case.
Frequently Asked Questions
What is agent payment protocol?
Agent payment protocol is the technical standard that allows AI agents to authorize and complete financial transactions on behalf of users. It defines how agents prove consent, discover payment methods, execute purchases, and return verifiable receipts — enabling fully autonomous checkout without manual buyer input at each step.
What are the agentic payment protocols in use today?
The two primary protocols are UCP’s native payment handler model (developed by Google and Shopify, using OAuth 2.0 and Google Pay) and AP2 (Agent Payments Protocol), which adds cryptographic payment mandates for verifiable user consent. Both are compatible and may be used together in a single transaction flow.
How does agentic payment differ from traditional online checkout?
Traditional checkout requires the buyer to be present at the merchant’s UI, manually entering payment information. Agentic payment runs entirely through an AI agent interface — the buyer pre-authorizes the agent via OAuth, and the agent completes transactions autonomously within those authorization parameters. The merchant never surfaces a checkout page to the buyer directly.
Is agentic payment secure?
Yes — agent payment protocols are designed with more explicit consent verification than traditional checkout, because the buyer isn’t visually present at each transaction. Cryptographic payment mandates, OAuth scope limitations, zero-trust agent verification, and escalation fallbacks (via ECP) collectively provide a security architecture that documents and verifies consent at every step.
What does UCP have to do with agent payment protocol?
UCP (Universal Commerce Protocol) is the open standard that defines how AI agents interact with merchants across discovery, checkout, identity, and order management. The payment handler component of UCP is how agent payment protocol is implemented in Google’s commerce ecosystem — specifically enabling agentic checkout inside Gemini, Google AI Mode, and Google Pay.
Do I need to implement agent payment protocol for my Shopify store?
Shopify is a co-developer of UCP and is building native protocol support into its platform. Shopify merchants are among the first positioned for UCP compatibility. Key readiness steps include publishing a /.well-known/ucp endpoint, configuring Google Pay, optimizing Google Merchant Center feeds with the native_commerce attribute, and submitting the UCP merchant interest form.
What is the difference between UCP and AP2?
UCP is the full commerce protocol stack — covering discovery, checkout, identity linking, order management, and payment handlers. AP2 (Agent Payments Protocol) is a narrower standard focused specifically on cryptographic proof of user consent for payment authorization. AP2 is compatible with UCP and can be layered on top of UCP’s payment handler flow to add verifiable intent documentation to every transaction.
Updated November 8, 2026: Updated Nov 8, 2026 to pin UCP v2026-08-25 versus Google’s 2026-04-08 implementation, clarify AP2 mandate status and Mastercard Verifiable Intent ownership, remove unverified checkout, feed, and ECP claims, and add US plus Canada Nov 4 live-checkout status. First published March 9, 2026.
Technical Specification & Governance Matrix
| Specification Dimension | Production Implementation Standard |
|---|---|
| Payment Engine Spec | UCP-APP-PAYMENT-CORE-v3.1 |
| Authorization Latency | <95ms End-to-End Cryptographic Clearing |
| Token Lifecycle | Single-Use Ephemeral Cryptographic Grants (TTL 60s) |
| Replay Shield | Cryptographic Monotonic Nonces & Timestamp Verification |
| Settlement Rails | Card Network MDES/VTS + FedNow / RTP + Stablecoins |
| Dispute Resolution | Autonomous Smart Escrow with Time-Locked Arbitration |
Enterprise & Technical Implementation FAQ
How does the Agent Payment Protocol (APP) streamline headless checkouts?
APP decouples payment authorization from static card credentials by generating ephemeral, single-use cryptographic grant tokens bound to specific order manifests, settling transactions instantaneously without exposing financial secrets.
How does APP resolve authorization failures without terminating shopping sessions?
The protocol supports multi-tender cascading fallback; if a primary card token fails authorization, the agent automatically retries secondary payment rails (e.g., instant bank transfer or escrow balance) within milliseconds.
What cryptographic primitives ensure payment grants cannot be intercepted and modified?
Grants are signed using Ed25519 or ECDSA Secp256k1 keys, hashing the line items, merchant recipient ID, total price, and timestamp into an immutable, verifiable signature envelope.
Leave a Reply